The accounts are closed. The project report is due in a few days. Yet delivery notes are still missing, timesheets need checking and a subcontractor’s progress statement is sitting in someone’s inbox. The controller requests information, the project manager tracks down agreements and the deadline keeps getting closer.
This is a familiar situation for many construction companies. Much of the time available is spent requesting, checking and correcting information that should already be in the system. By the time the actual result is reliable, the report is due and the forecast at completion still needs updating. There is hardly any time left for a thorough analysis.
A smooth month-end close therefore starts with how information is recorded and followed up during day-to-day operations.
Getting the figures right is the starting point, not the end goal
A controller has only a limited window between the accounting close and the presentation of the project report. Getting the figures right often takes up so much of that time that the real purpose comes under pressure: analysing, looking ahead and advising on the corrective action needed.
This highlights an important difference between accounting and project control. Accounting records what has happened. The controller uses reliable, up-to-date figures to assess where the project is heading. What costs are still to come? What does current productivity mean for the remaining work? And is the forecast final margin still achievable?
If the controller is mainly reconstructing the past, the report shows where the project stood, but offers too little insight into where it will end up.
What is left unresolved during the month returns at month-end
On site, delivery of the work comes first. Materials must arrive on time, crews need to keep working and problems require immediate solutions. The administrative work often follows later.
A delivery has arrived, but the delivery note has not been recorded. A subcontractor has completed work, but their progress statement still needs checking. A machine stays on site longer, without the additional hire period being entered in the system. The people involved know what has happened, but that knowledge is not yet available for reporting.
At month-end, this information still has to be collected. Reporting then depends on individual employees and the agreements they may have made. What would have been straightforward to record during the work becomes a search for information a few weeks later.
Closed accounts do not automatically mean complete project reporting
Reliable project reporting requires more than checking which invoices have been processed. Materials may have been delivered and work carried out for which no invoice has yet been received.
Suppose a subcontractor carries out work in September but only invoices it in October. If the September report is based solely on posted invoices, those costs are missing. If the corresponding revenue has already been recognised, the margin looks better than it really is. A month later, the costs appear and the result seems to deteriorate suddenly. Site performance has not necessarily worsened: the information entered the figures at different times.
Costs, revenue and progress must therefore relate to the same reporting period. Delivery notes, approved progress statements, timesheets and plant usage are important sources. Where information is missing, a substantiated estimate may be needed. This must be tracked so that costs are not counted twice when the actual information is processed.
The question at month-end is therefore not just: “Has everything been posted?” It is also: “Have we captured everything that belongs to this period?”
Clear responsibilities, supported by software
A reliable month-end close requires more than a deadline. Everyone needs to know which information they must provide, when it must be available and which checks are required beforehand. Forwarding a delivery note is not the same as checking and recording a delivery.
Agree clearly on what must be ready at month-end:
- Deliveries and completed work have been recorded and checked.
- Labour hours and plant usage are complete and allocated to the correct projects.
- Missing costs, disputed amounts and uncertainties have been reported and explained.
- Progress and the forecast costs of the remaining work have been updated.
Align these arrangements with the accounting close and the project reporting deadline. Each person remains responsible for their own information. The site team confirms deliveries and completed work, procurement monitors contractual agreements and accounting processes invoices. The project manager assesses progress and the remaining work. The controller checks that the information is consistent and analyses its implications for the forecast final result.
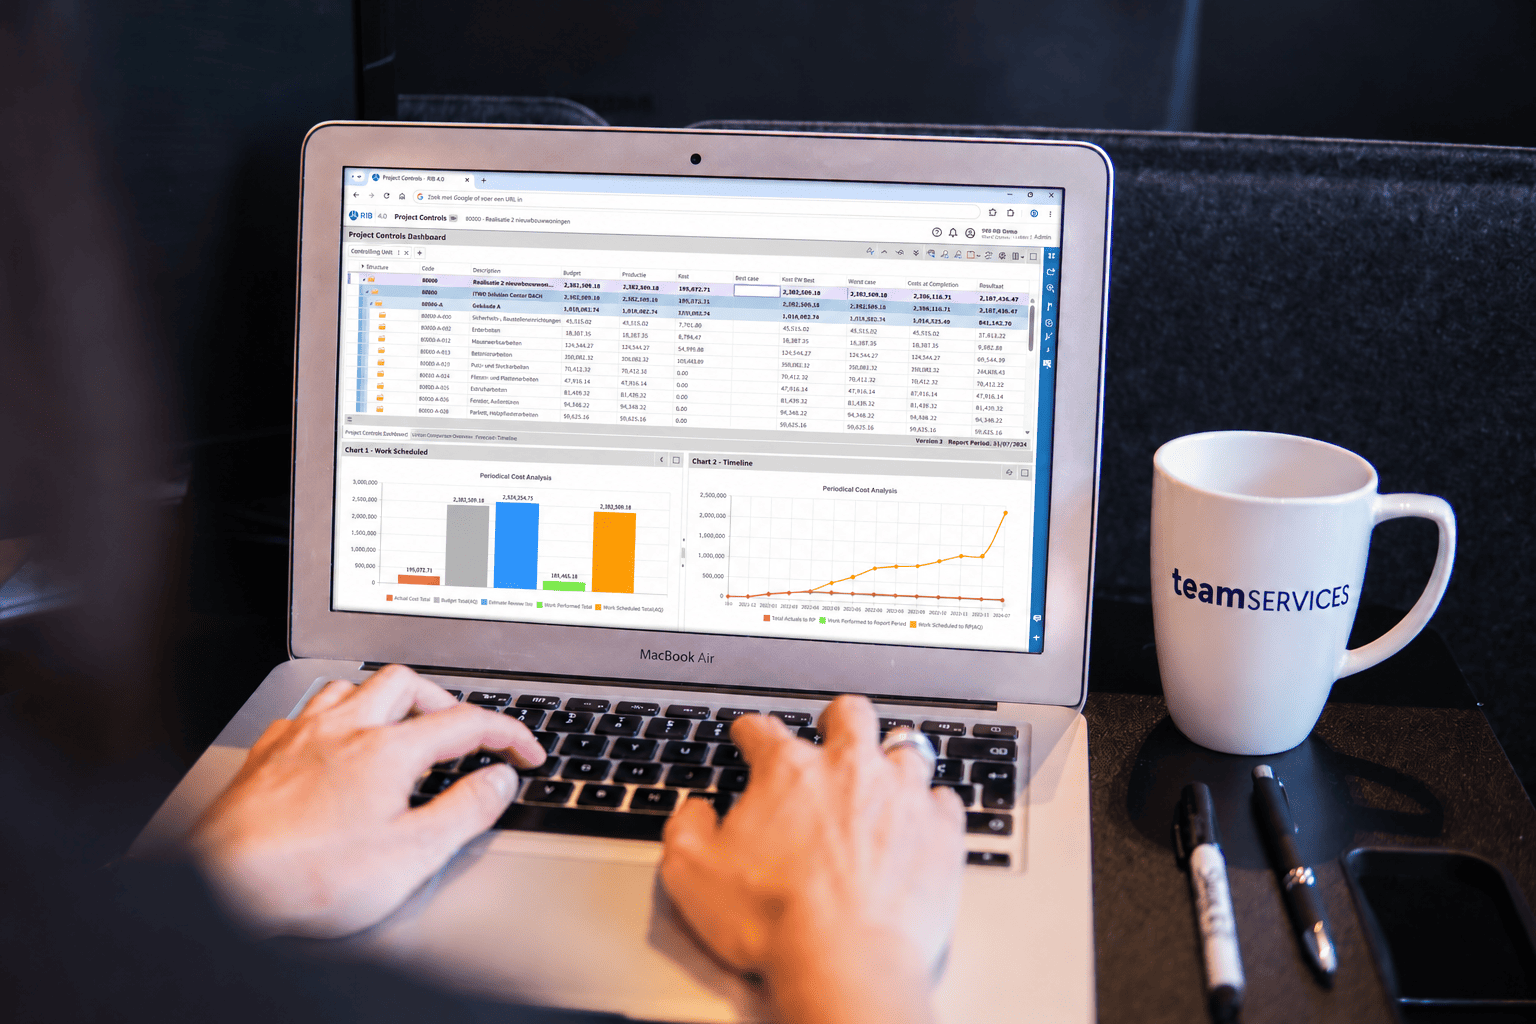
An integrated system supports this collaboration. Linking purchase orders, delivery notes, progress statements and invoices makes it easier to see what is missing or still awaiting approval. But this only works when it is clear who records, checks and follows up the information.
Recurring corrections also deserve attention. If the same costs are missing every month, the underlying process needs to be addressed. Otherwise, the search simply starts again at the next close.
More time to look ahead
A well-organised month-end close frees up time to examine, together with the project manager, what the figures mean for the remaining work. Will a cost overrun recur? Does the forecast need adjusting? Could a different construction method, procurement decision or schedule still improve the result?
At Teamservices, we connect information from site teams, procurement and accounting with the needs of project cost control. Through clear responsibilities and appropriately configured software, we help make reliable figures available on time, leaving room for analysis, forecasting and corrective action.